HDFC RuPay Credit Card Rejected? The Real Reasons and What to Do Next
HDFC RuPay credit card rejected? Learn the common reasons, from CIBIL score to video KYC, and the steps that improve your chances before you reapply.
Getting a "Disapproved" message feels personal, but it usually isn't. Banks decline applications for a handful of common reasons, and most of them can be fixed. So if your HDFC RuPay credit card rejected message just arrived, read this before you try again. Applying again the same week is the one thing that makes it worse.
Facts checked on 24 October 2026 against HDFC Bank's RuPay credit card page. Fees, rewards and offers change often, so confirm them on the application screen before you apply.
Why Was My HDFC RuPay Credit Card Rejected?
HDFC rarely gives a detailed reason. Still, almost every decline falls into one of the groups below. Go through them honestly, and you'll usually spot yours.
Your credit score is low or too thin
This is the most common reason. A late EMI, a settled loan or a high card balance pulls your CIBIL score down. On the other hand, having no credit history at all also makes banks careful. You can check your report for free on CIBIL's website.
Your income is below the card's bar
Each HDFC card has its own minimum income. If you applied for a card above your salary level, the system declines it automatically. In that case, an entry card like Pixel Go or Freedom is a better first step.
Too many applications in a short time
Every application adds a "hard enquiry" to your credit report. Three or four in a month tell banks that you badly need credit. So space them out.
Existing EMIs are too high
Banks look at how much of your income already goes to loans. If EMIs take up a large share, they won't add a credit card on top.
A KYC or detail mismatch
A different spelling of your name, an old address or a mobile number not linked to Aadhaar can all stop the file. Also, a video KYC done from another city can be a red flag.
HDFC doesn't serve your pin code
Sometimes the problem is simply location. Banks issue cards only in areas they cover, and a few pin codes are left out.
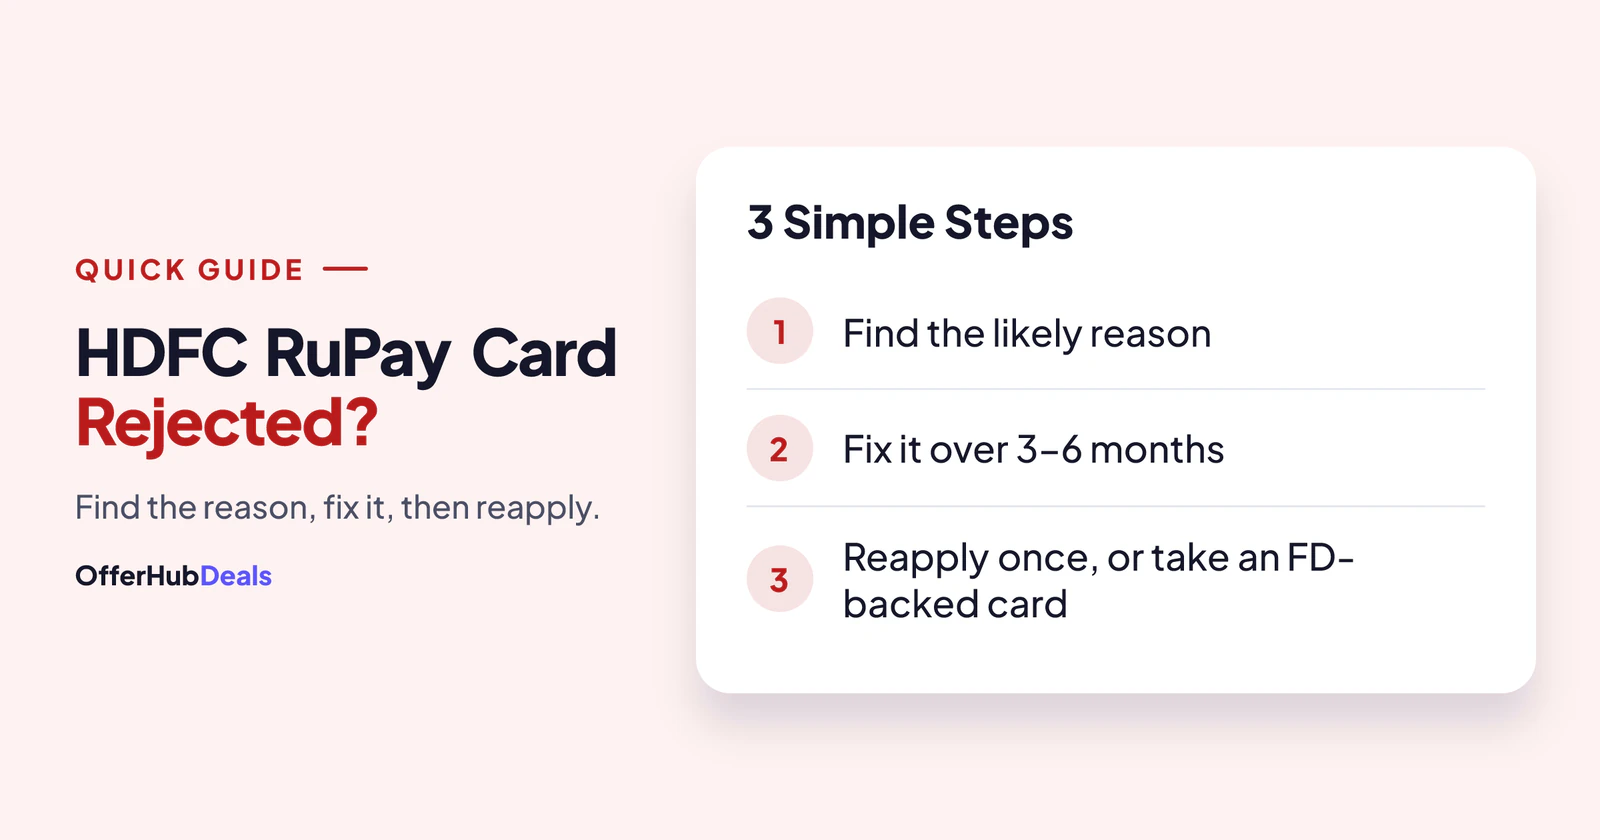
What to Do After an HDFC RuPay Credit Card Rejected Message
First, don't reapply straight away. Wait at least three months, ideally six, while you fix the cause. Then download your CIBIL report and check it line by line. If you find a loan you never took or a payment wrongly marked late, raise a dispute with CIBIL.
Next, work on the cause. Pay every bill on time, bring your card balances below 30% of their limits, and close small loans if you can. If the problem was KYC, link your mobile to Aadhaar and make sure your PAN and Aadhaar details match.
You can also call HDFC customer care with your application reference number. They usually share only a broad reason, such as "credit" or "policy". Still, combined with your CIBIL report, that is often enough to work out what went wrong.
A Faster Route When Your HDFC RuPay Card Is Rejected
If you need a card now, consider a card backed by a fixed deposit. You open an FD, and the bank gives you a limit against it. Because your money secures the card, there's usually no income or score check. HDFC offers this route on some cards, including the FD-backed version of Pixel Go explained in our Pixel Go for students guide.
Use that card for small spends and pay in full every month. After six to twelve months, your score usually improves enough for a regular card.
Reapplying After Your HDFC RuPay Credit Card Was Rejected
Apply for one card only, and pick one that matches your income. Then follow our step-by-step application guide carefully, especially the video KYC part. Small slips there cause more declines than people think.
Check your HDFC RuPay card options →Affiliate link: OfferHubDeals may earn a commission if your card is approved. It costs you nothing, and it does not change what we write.
Final Word
An HDFC RuPay credit card rejected message is a pause, not a permanent no. Find the reason, give it a few months, and reapply for the right card. In the meantime, an FD-backed card can start building the history you need.
More HDFC RuPay card guides
- HDFC RuPay credit card: benefits, fees and which one to pick
- How to apply, and how to check your application status
- Use your HDFC RuPay card on UPI, and fix UPI errors
- EMI, PayZapp and SmartBuy explained
- CashPoints not credited? How to get them
- How to close an HDFC credit card safely
- RuPay vs Visa: which network should you choose?
- HDFC vs SBI RuPay credit card
Frequently asked questions
Why was my HDFC RuPay credit card application rejected?
Common reasons are a low or thin CIBIL score, income below the card's bar, too many recent applications, high EMIs, KYC mismatches or an unserved pin code.
How soon can I reapply after an HDFC rejection?
Wait at least three months, ideally six, and fix the likely reason first. Each new application adds an enquiry to your credit report.
Does HDFC tell you why a card was rejected?
Customer care may share a broad reason with your reference number. Your CIBIL report usually explains the rest.
Can I get a credit card after rejection without income proof?
Yes, an FD-backed card usually needs no income proof or score check, because the deposit secures the limit.
HDFC credit card reject kyu hota hai?
Zyada tar CIBIL score kam hone, income kam hone, baar-baar apply karne ya KYC details match na hone ki wajah se.