HDFC RuPay Credit Card EMI, PayZapp and SmartBuy: How to Use Them and What They Cost
How HDFC RuPay credit card EMI works, the real cost with an example, plus how PayZapp and SmartBuy help you manage the card and earn more rewards.
Your HDFC card comes with three tools that most people never fully use: EMI conversion, the PayZapp app and the SmartBuy portal. Used well, they save money. Used carelessly, EMI in particular can cost far more than you expect. So let's start with how HDFC RuPay credit card EMI works, then cover PayZapp and SmartBuy.
Facts checked on 24 October 2026 against HDFC Bank's RuPay credit card page. Fees, rewards and offers change often, so confirm them on the application screen before you apply.
How HDFC RuPay Credit Card EMI Works
HDFC calls it SmartEMI. You make a big purchase on your card, and then you convert it into monthly instalments. HDFC's SmartEMI page lists tenures from 6 to 48 months.
You can convert a purchase through MyCards, net banking, PayZapp or customer care. However, you have to do it within 60 days of the purchase. A few types, such as gold and jewellery, can't be converted at all.
There's one more option for RuPay cards. If you paid by UPI, some apps let you convert that payment to EMI as well. In Google Pay, for example, you open the payment in your history and tap "Check EMI plans".
What HDFC RuPay Credit Card EMI Really Costs
This is where people get surprised. First, there's a processing fee of up to ₹849 plus GST. Next, interest is charged on the balance, and HDFC's published rates for April to June 2026 ranged from about 10.8% to 25% a year. On top of that, GST applies to the interest and the fee.
Here's a simple example. Say you convert a ₹30,000 phone into 12 EMIs at 15% a year. Your EMI is about ₹2,710, so you pay roughly ₹2,500 in interest. Add the fee and GST, and the extra cost comes close to ₹4,000.
Also, any reward points you earned on that purchase are reversed when you convert it. And if you close the EMI early, there's a foreclosure charge of about 3% of the balance, plus GST.
So EMI is worth it only when the alternative is worse, like paying the full card interest of around 3.6% a month. If a shop offers no-cost EMI at checkout, that's usually cheaper. Our no-cost EMI explainer shows what to check.
PayZapp: HDFC's App for Your Card
PayZapp is HDFC's payments app, and it works as the control room for your card. You can see your bill, set the PIN, lock the card, change limits and convert purchases to EMI. Pixel cards live entirely inside it.
It also pays extra on one card. The HDFC UPI RuPay credit card gives 3% CashPoints on PayZapp transactions, the same rate as groceries and dining. So paying bills or recharges through PayZapp with that card earns more than doing it elsewhere.
SmartBuy: Where HDFC Rewards Go Further
SmartBuy is HDFC's own shopping and travel portal. You book flights, hotels, trains and gift vouchers there, and the bank adds extra rewards or discounts on top.
The value depends on your card. For instance, the IRCTC HDFC card earns 5% cashback on train tickets booked through SmartBuy. Freedom card holders can use CashPoints to pay for up to 50% of a flight or hotel booking. Offers change every month, so check the SmartBuy page before you book.
A Simple Rule for All Three
Use PayZapp to keep an eye on the card, SmartBuy when you're booking travel anyway, and EMI only for real emergencies. For everything else, pay the full bill on time. That's how an HDFC RuPay card actually saves you money. If you're still choosing a card, start with our HDFC RuPay card guide.
Apply for an HDFC RuPay credit card →Affiliate link: OfferHubDeals may earn a commission if your card is approved. It costs you nothing, and it does not change what we write.
Final Word
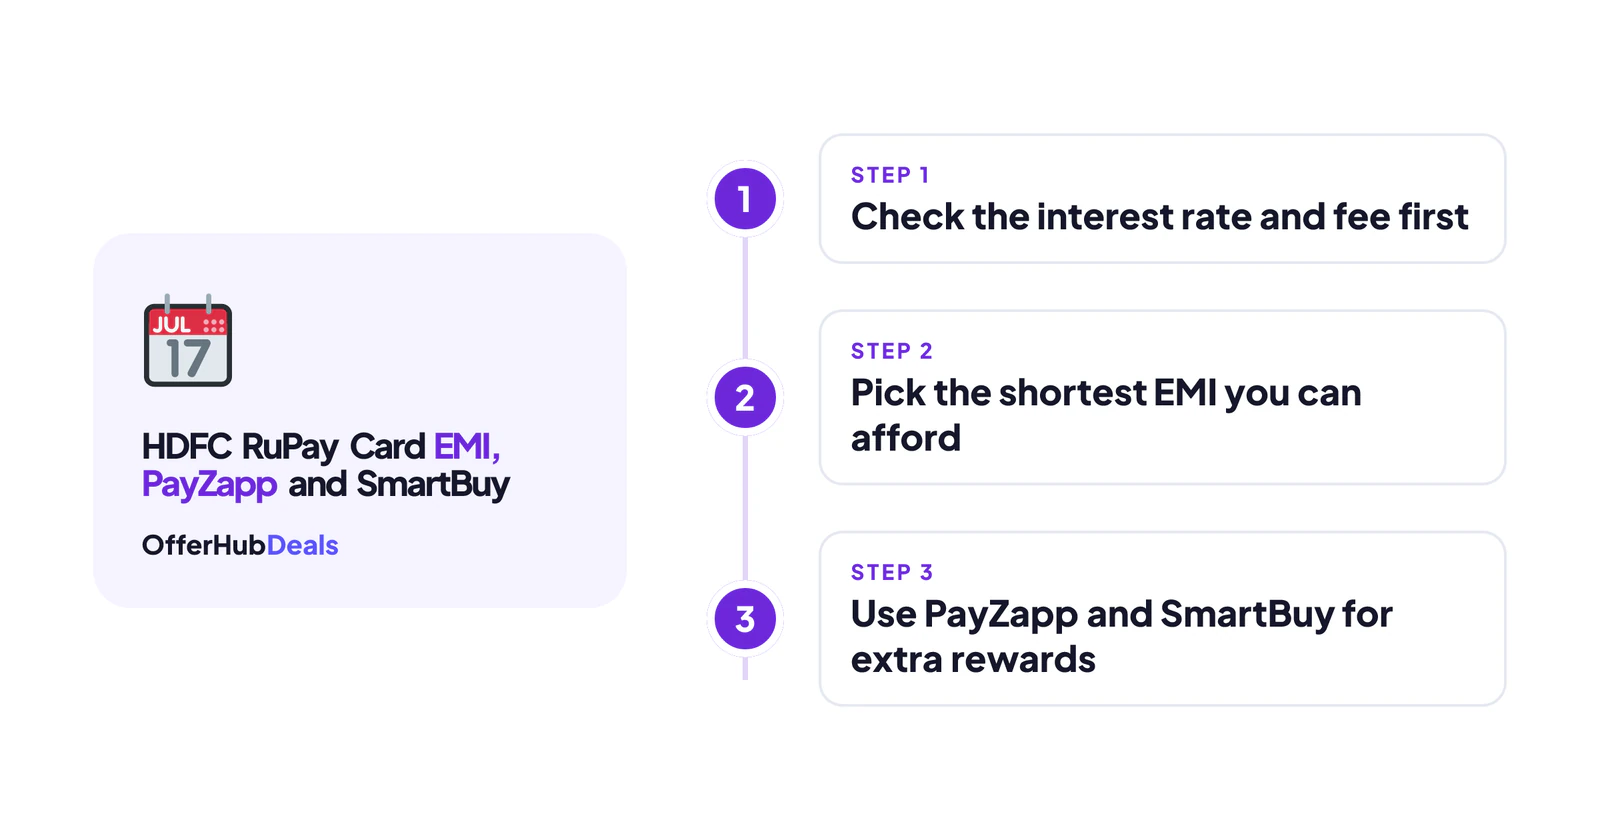
HDFC RuPay credit card EMI is a handy safety net, but it is a loan, with fees and GST. So compare the total cost before you convert, and pick the shortest plan you can manage. Meanwhile, PayZapp and SmartBuy are free to use and quietly add value, so make them a habit.
More HDFC RuPay card guides
- HDFC RuPay credit card: benefits, fees and which one to pick
- How to apply, and how to check your application status
- Application rejected? Reasons and what to do next
- Use your HDFC RuPay card on UPI, and fix UPI errors
- CashPoints not credited? How to get them
- How to close an HDFC credit card safely
- RuPay vs Visa: which network should you choose?
- HDFC vs SBI RuPay credit card
Frequently asked questions
How do I convert an HDFC credit card purchase to EMI?
Use MyCards, net banking, PayZapp or customer care within 60 days of the purchase, then pick a tenure between 6 and 48 months.
What is the processing fee for HDFC SmartEMI?
HDFC lists a processing fee of up to ₹849 plus GST. Interest and GST are charged on top.
Can I convert a UPI payment on my RuPay credit card to EMI?
Yes, some UPI apps like Google Pay let you check EMI plans for eligible RuPay credit card payments in your history.
Do I lose reward points if I convert to EMI?
Yes. HDFC reverses reward points earned on a purchase that is converted to SmartEMI.
HDFC credit card EMI kaise kare?
MyCards ya PayZapp kholo, purchase chuno aur EMI tenure select karo. Pehle fee aur interest zaroor dekh lo.